
Banking with Aditya YouTube channel analysis
Banking with Aditya is a YouTube channel with 1.1K subscribers and 293.7K total views, and an estimated $6 – $32/mo revenue. This analysis breaks down its outlier videos, content strategy, similar channels, revenue & valuation estimate.
Analysis generated with AI from public YouTube data. Revenue and valuation figures are estimates derived from public data, not financial advice.
Banking with Aditya Channel Overview
lifetime totalsBanking with Aditya Outlier Videos
breakouts ≥1.5× recent median
Banking with Aditya Top Videos
biggest ever 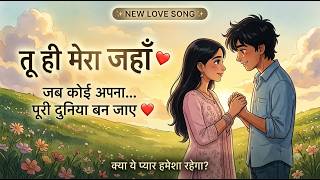



Do not acquire due to the tiny subscriber base (1,090) and severe brand dilution from uploading unrelated music, but replicate the Hindi-language retail banking tutorial model which shows strong search-driven hit-rates for government schemes.
Banking with Aditya Niche & Positioning
A Hindi-language utility channel explaining basic banking rules, hidden fees, and government savings schemes for everyday retail consumers.
Banking with Aditya Content Strategy
Focuses heavily on evergreen search-based retail banking tutorials and government schemes, occasionally chasing regulatory updates, alongside highly anomalous music uploads.
Banking with Aditya Outlier Playbook
the repeatable breakout formulaBreakouts on Banking with Aditya come from Hindi, search-led explainers that simplify a high-intent, family-money topic with a concrete 2026 update. The strongest repeatable winner is not generic banking tips, but government/safe-savings schemes for common households: e.g., “Sukanya Samriddhi Yojana 2026” won because it combines a trusted scheme, daughter/family emotion, tiny starting amount “₹250 से शुरुआत,” and complete rules in one video: interest, maturity, withdrawal. The second outlier, the Ghibli-inspired Hindi love song, is an off-niche novelty/emotional format and should be treated as a separate experiment, not the main banking formula.
[Scheme/Product Name] 2026 | [small money hook / shocking benefit] से शुरुआत, [Interest/Benefits], [Maturity/Charges/Withdrawal Rules] पूरी जानकारी
- 1Make the next videos around government or bank products with broad household search demand, especially “Sukanya Samriddhi Yojana 2026,” “Jan Dhan Account Benefits,” “PPF 2026,” “Senior Citizen Savings
- 2Use a complete-rule explainer format in Hindi: start with who it is for, minimum amount, current interest/benefit, maturity period, withdrawal rules, tax/charges, documents needed, and exact step-by-s
- 3Lead the title and opening 5 seconds with a concrete number or benefit: “₹250 से शुरुआत,” “₹10,000 तक फायदा,” “बिना minimum balance,” “इतना interest मिलेगा,” or “पैसे कब निकाल सकते हैं?” Avoid vague h
- 4Package every banking video as an updated 2026 guide, even if the scheme is old: mention “latest interest rate,” “new rules,” “documents,” and “withdrawal/maturity rules” so it feels current like the
- 5Keep the off-niche music/Ghibli experiment separate: if repeating it, title it clearly as an emotional Hindi song with a strong visual aesthetic, but do not mix it into the core banking audience unles
Banking with Aditya Performance Drivers
Banking with Aditya Topic Clusters
Banking with Aditya Growth Opportunities
untapped whitespace- Create direct comparison videos of interest rates across major Indian banks (SBI vs HDFC vs ICICI) to capture high-intent search traffic.
- Develop step-by-step visual walkthroughs of popular mobile banking apps to assist non-tech-savvy users.
- Produce dedicated tax-saving guides (Section 80C) during the Indian financial year-end (January-March) to capture seasonal search surges.
How Replicable Is Banking with Aditya
The content relies entirely on publicly available banking guidelines, interest rates, and government scheme rules, requiring no proprietary access or specialized talent.
Banking with Aditya Content Risks
- Severe audience dilution and algorithmic confusion caused by mixing romantic music uploads with retail banking tutorials.
- Low viewer loyalty and high search-dependence, leading to one-off views where users solve a specific problem and immediately leave without subscribing.
- Intense competition from thousands of larger personal finance creators covering the exact same public banking updates.
Who Watches Banking with Aditya
estimated audienceEstimated from public channel data — titles, descriptions, metadata and co-watched channels. Not YouTube Analytics. medium confidence
This channel caters to everyday Indian retail banking consumers, particularly young families and middle-class individuals who want to navigate the Indian banking system without losing money to hidden fees. The audience relies on simple Hindi explanations to understand government welfare schemes, manage basic savings accounts, improve credit scores, and stay updated on digital payment rules like UPI.
Predominantly male, with a notable female segment interested in family savings s
Highly concentrated in India, particularly semi-urban and tier-2/3 cities where Hindi is the primary language of instruction and daily communication.
What Banking with Aditya's Audience Cares About
- Unexpected bank account deductions and hidden charges
- Confusion over changing UPI and digital payment regulations
- Low credit scores preventing access to affordable loans
- Complex banking terminology and bureaucratic procedures
- To protect hard-earned money from unnecessary bank fees
- To secure their children's future through schemes like Sukanya Samriddhi Yojana
- To become financially self-reliant and digitally literate
Budget-conscious, cautious adopters of digital banking who prefer low-risk financial instruments like FDs and government post office schemes.
- How to avoid hidden charges in SBI and other major Indian banks
- Step-by-step guide to opening a Sukanya Samriddhi Yojana account
- How to check and improve your CIBIL score quickly for personal loans
- New UPI transaction rules and wallet charges explained
- Pros and cons of taking a loan against Fixed Deposit (FD)
Prefers Short to medium-length videos (3 to 6 minutes) that deliver videos, educational, protective, simple, and trustworthy..
Inferred from: Hindi-language titles focusing on Indian public sector banks like SBI · Content centered on Indian government schemes like Sukanya Samriddhi and Jan Dhan · Co-watch overlap with Indian taxation and personal finance channels like GST PLATFORM
The co-watch graph is heavily split between Indian personal finance/taxation and Eastern European geopolitical news, indicating a highly diluted audience profile.


Track your whole niche in Competitor Studio
These are just the closest channels. Competitor Studio maps 1,000+ direct & adjacent channels in your niche — with outlier detection and ongoing tracking.
- Track 1,000+ direct & adjacent competitors
- Outlier video detection
- AI-powered video insights
Banking with Aditya Revenue & Valuation
from public dataBased on your current cash flows, your channel's valuation is estimated between $79 and $673, with a floor of $60 and high confidence in this range. This valuation reflects your baseline performance, but implementing key operational levers offers the potential to significantly increase the overall value of your media asset.
Estimates derived from public data (earnings history + comparable channels). Not an offer, appraisal, or financial advice.
Frequently asked questions about Banking with Aditya
- How many subscribers does Banking with Aditya have?
- Banking with Aditya has 1.1K subscribers on YouTube, built up over roughly 5.6 years on the platform. Its videos average about 2.7K views each.
- How many views does Banking with Aditya have?
- Banking with Aditya has accumulated 293.7K total views across 108 uploads, averaging roughly 143 views per day since launch.
- How many videos has Banking with Aditya posted?
- Banking with Aditya has published 108 videos on YouTube, with recent uploads averaging about 3:46 in length.
- How engaged is Banking with Aditya's audience?
- Over its lifetime, Banking with Aditya has averaged about 269 views for every subscriber, a sign of how far its videos travel beyond the core subscriber base. On a per-video basis it draws roughly 2.7K views.
- How much money does Banking with Aditya make?
- Banking with Aditya's estimated YouTube revenue is $6 – $32 per month, including advertising and sponsorships (ad revenue alone is an estimated $4 – $11 per month). These are estimates derived from public data, not exact earnings.
- What is Banking with Aditya's channel worth?
- Banking with Aditya's YouTube channel is estimated to be worth $79 – $673, benchmarked against comparable channels. This reflects the value of the channel as a media asset, not the creator's total net worth.
- What is Banking with Aditya's most popular video?
- Banking with Aditya's most-viewed video is "Sukanya Samriddhi Yojana 2026 | ₹250 से शुरुआत, Interest, Maturity, Withdrawal Rules पूरी जानकारी", with 176 views — roughly 2.7× the channel's typical video.
- What is Banking with Aditya's biggest recent breakout video?
- Banking with Aditya's biggest recent breakout is "Sukanya Samriddhi Yojana 2026 | ₹250 से शुरुआत, Interest, Maturity, Withdrawal Rules पूरी जानकारी", which pulled 176 views — about 2.7× the channel's recent median.
- What kind of content does Banking with Aditya make?
- Banking with Aditya is best described as Indian Retail Banking & Government Schemes. A Hindi-language utility channel explaining basic banking rules, hidden fees, and government savings schemes for everyday retail consumers.
- Does Banking with Aditya post Shorts or long-form videos?
- Banking with Aditya publishes primarily long-form videos (about 100% of recent uploads), averaging around 3:46 in length.
- What topics does Banking with Aditya cover?
- Banking with Aditya's catalogue spans Government Welfare & Savings Schemes, Bank Account Management & Fee Warnings, Credit Scores & Debt Management, UPI & Digital Payment Regulations and Experimental Music Content. These recurring themes make up the bulk of the channel's uploads.
- Who watches Banking with Aditya?
- Banking with Aditya's audience skews 25-34, predominantly male, with a notable female segment interested in family savings s and based highly concentrated in india, particularly semi-urban and tier-2/3 cities where hindi is the primary language of instruction and daily communication.. This channel caters to everyday Indian retail banking consumers, particularly young families and middle-class individuals who want to navigate the Indian banking system without losing money to hidden fees. The audience relies on simple Hindi explanations to understand government welfare schemes, manage basic savings accounts, improve credit scores, and stay updated on digital payment rules like UPI. These are estimates inferred from public channel data, not YouTube Analytics.
- What is Banking with Aditya's audience interested in?
- Viewers of Banking with Aditya tend to be interested in Retail banking procedures, Government-backed saving schemes, Personal debt management, Digital payment updates and Avoiding banking penalties. Estimated from the channel's content and the channels its viewers co-watch.
- What channels are similar to Banking with Aditya?
- Channels with audiences similar to Banking with Aditya include GST PLATFORM, XY- Axis Education and Thefynprint. The co-watch graph is heavily split between Indian personal finance/taxation and Eastern European geopolitical news, indicating a highly diluted audience profile.
- How often does Banking with Aditya post?
- Banking with Aditya uploads about 3.5 videos per week (roughly 15 per month).
- Is Banking with Aditya still active on YouTube?
- Yes — Banking with Aditya is actively posting. Its most recent upload was 14 days ago.
- How long has Banking with Aditya been on YouTube?
- Banking with Aditya has been active on YouTube for about 5.6 years, growing to 1.1K subscribers over that time.
How this analysis was made
- Source: public YouTube channel & video data (8 recent videos sampled).
- Outlier videos: uploads with ≥1.5× the channel's recent median views.
- Revenue & valuation: estimated from public earnings signals and comparable channels — ranges, not exact figures.
- Last updated: 10/12/2026.